

April 1, 2025
When Brian Davis had an interaction with a La Capitol Federal Credit Union member who had questions about a HELOC,4 he was prepared to treat her needs as top priorities. Davis, a Mortgage Loan Originator, works to improve the financial well-being of the credit union’s member-owners and his role highlights a very important credit union difference in our communities.
La Capitol, and other credit unions across the country, are a small but vital financial option for consumers. By working to protect credit unions’ not-for-profit status, you can help provide needed, lower-cost financial products to those who need it most.
Davis’ interaction shows the impact credit unions bring to the table. Our member had questions about a HELOC or home equity line of credit.4 Davis realized something very important – the member could save a significant amount of money by refinancing the current home equity loan she had with another financial institution.
La Cap was able to reduce the member’s interest rate from 8 percent to 6 percent on a 20-year fixed-rate home equity loan, saving her nearly $20,000 over the life of the loan. Instead of turning into profit for stockholders, that will be $20,000 that stays with the credit union member, a part owner in the not-for-profit cooperative.
Why Protect Credit Unions?
Because of their structure, credit unions can offer significant advantages:
- Earnings: The dividends paid on deposits and savings are often higher than what banks offer. This often includes share certificates1 (similar to certificates of deposit at banks) and individual retirement accounts,2 for example. Likewise, the rates charged for mortgages,3 home equity lines of credit (HELOCs),4 vehicle loans,5 and personal loans6 are often lower for credit union members than they are for bank customers.
- Securities: Turning a profit through investments is a major focus for most banks because they pay dividends to shareholders, but credit unions must disclose all profits and reinvest them back into the credit union for the benefit of all members.
- Fees: Credit unions typically provide all of the financial services that banks do, but they do it for less. Fees are often lower than those for banks, and that can extend to everything from monthly service fees on accounts to mortgage closing costs. Requirements may be less stringent — lower minimum account balances, for example. Credit unions exist to serve their members — not simply profit from them. In fact, many credit unions instead offer perks to their members through extra services or favorable terms for transactions.
Help by Contacting Lawmakers
The new Congress is rapidly advancing tax reform initiatives, which could potentially introduce a new tax on credit unions and, by extension, on the millions of members they serve—yes, that includes you. Imagine credit unions as community lifelines, providing essential financial services to over 140 million Americans.
A new tax on these institutions is not just a policy change; it's a direct financial impact on a significant portion of the population. It's crucial that we take immediate action to communicate to lawmakers that this proposed tax is essentially a tax hike on everyday Americans who rely on credit unions for affordable financial solutions. Let's ensure our voices are heard and protect the financial well-being of our communities.
With just a few clicks, you can instantly send a pre-filled message to your U.S. Representatives and Senators. It's quick, easy, and critical—let them know you oppose any new tax proposals that could hurt credit unions. Every message counts, and your voice can make a real impact today!
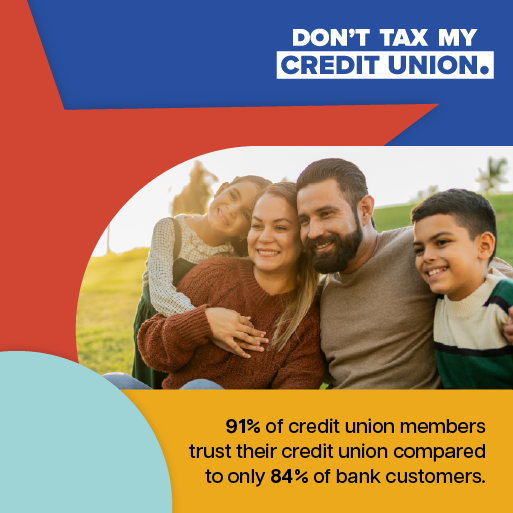
Tell Congress: Don’t tax my credit union—it’s a tax on me.
Disclosures
1 La Capitol Certificate Accounts are term Share Accounts. The APY is fixed at the time you make the initial deposit to open or renew the account, and will not change during the term of the Certificate. The APY given above assume dividends remain in the account until maturity. A withdrawal of dividends will reduce earnings. Dividends earned are posted and compounded monthly unless otherwise paid, except for the 91-Day Account, to which earnings are posted at maturity. You may choose to have your earnings compounded in the Certificate Account, or transferred to your La Cap savings or checking account. Applicable fees and other conditions could reduce the earnings on your account. Substantial penalty for early withdrawal. Effective Date: 10/09/2026
2 IRA Certificate Account is a term share account. The Annual Percentage Yield is fixed at the time you make the initial deposit to open or renew the account, and will not change during the term of the Certificate.
IRA Floating Rate Account is a variable rate account with no maturity. No minimum deposit is required to open this account or to obtain the disclosed Annual Percentage Yield. La Cap may change the dividend rate for your account as determined by the credit union Board of Directors.
Dividends earned are posted and compounded monthly. Applicable fees and conditions could reduce the earnings on your account. Substantial penalties for early withdrawal.
3 Loans are available to qualified, creditworthy members. The amount of your loan and the term will affect your interest rate. The rate you qualify for will depend on a review of your credit history. Ask for complete details.
4 APR = Annual Percentage Rate. HELOC interest rates are variable, based on an index plus a margin. The index is PRIME as published in the Wall Street Journal. The introductory rate is as low as 3.99% APR and is effective for 6 months (180 days) from the consummation date. The non-introductory APR range is 7.25% to 13.00% as of Effective date: 10/01/26. The minimum loan amount is $10,000. La Capitol FCU will pay up to $1,500 of closing cost. Closing cost does not include full appraisal fee if appraisal is required. La Cap will pay the closing costs; however, these costs will be charged back to the borrower(s) if the HELOC is closed within twenty-four (24) months of origination. Other restrictions may apply. Equal housing lender. NMLS # 411413. Effective date: 10/01/26
5 APR = Annual Percentage Rate. Membership is required and subject to approval. Membership requires $5.00 par balance in a primary savings account. Offer available to qualified creditworthy members. Vehicle Loans are subject to approval. New vehicle rates apply to model year 2023 and newer. Used vehicle rates apply to model year 2022 and older. Not everyone will qualify for the lowest rate available. Loan approval, rates, loan to value (LTV), and terms are based on certain credit criteria and worthiness. Model year, LTV, and adding payment protection may change the rate, payment, and term. Effective Date: 10/13/26
6 * Membership required. To receive loan proceeds Regular Share Account with a $5.00 par balance is required. APR = Annual Percentage Rate. 9.99% APR is the lowest rate available for the advertised product. Minimum loan amount is $1001.00. Loan approval, rates, and terms are based on certain credit criteria and worthiness not everyone will qualify for the lowest rate available. The maximum term of payment available is 60 months. The maximum rate for a La Cap personal loan is 18% APR. Payment Example: A loan amount of $9,000 for 48 months at 9.99% APR has an estimated monthly payment of $228.18. Adding payment protection may change the rate, payment, and term. Any deferment of payment(s) during the life of the loan may result in an increased APR for the statement cycle(s) of the deferred payments. Offer valid for unsecured loans only and cannot be combined with any other offer. Other restrictions may apply. Contact a La Cap representative for details. Effective Date: 10/1/2026